
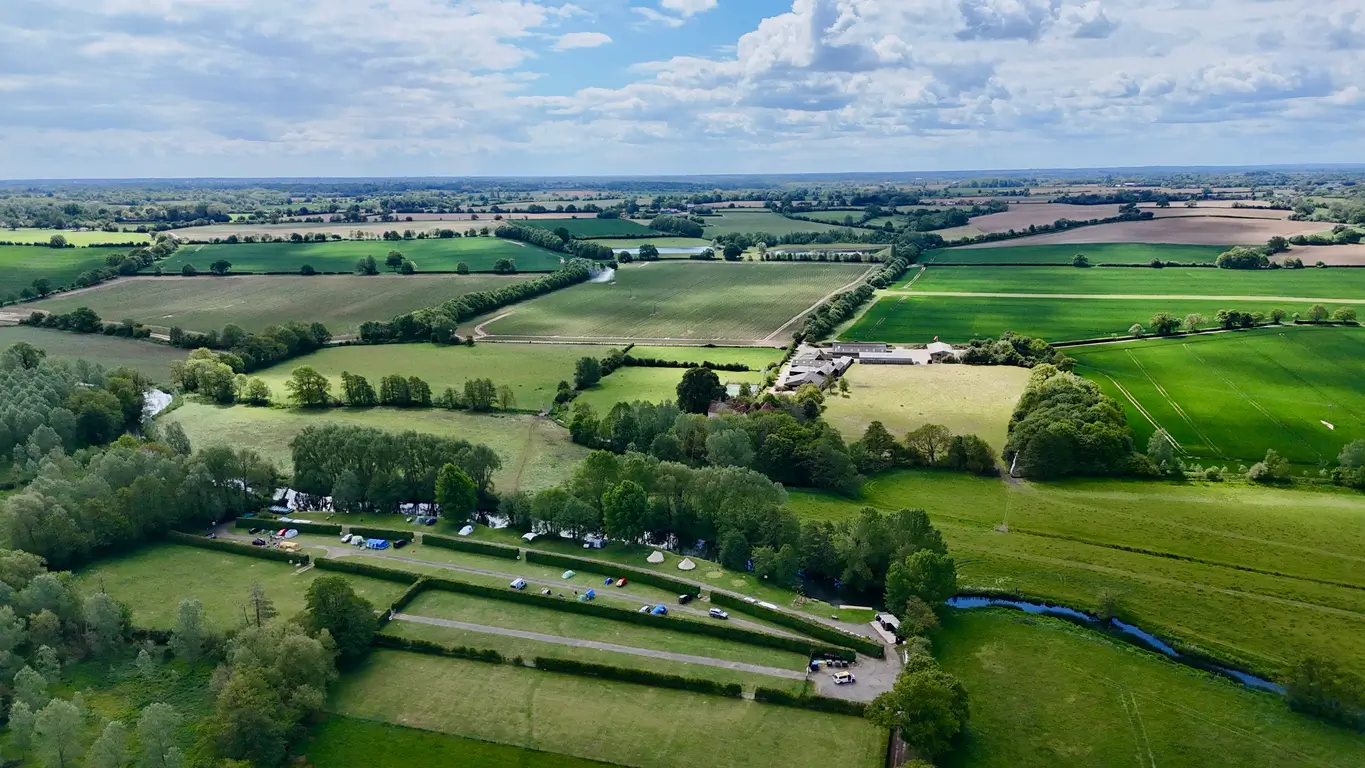
Campsite insurance and static caravan insurance cover different people, property and risks. Campsite insurance by Ripe is designed for eligible campsite operators, while static caravan insurance by Ripe is designed for an eligible holiday caravan owned by an individual.
At a tent campsite, shared shower blocks, toilets and walkways are examples of areas the operator may be responsible for. These are separate from a privately owned caravan. Being located on an insured campsite does not mean a caravan is covered by the campsite’s policy.
What is campsite insurance?
Campsite insurance by Ripe is business insurance for the person or organisation responsible for running a campsite. It can cover the site’s activities, employees, buildings, equipment and facilities, depending on the options selected.
Cover can include:
Public and Products Liability up to £10 million
Employers’ Liability up to £10 million
Buildings cover up to £500k
Fixtures, fittings and tenants’ improvements up to £100k
General contents cover up to £250k
Stock cover up to £10k
Business Interruption cover up to £500k
Cover for ground-maintenance equipment and playgrounds
For example, a campsite policy may respond if a visitor is injured in an insured area, an employee is hurt while carrying out their work, or a storm damages an insured reception building. Whether a claim is covered will depend on the circumstances, the policy wording and selected cover.
Ripe’s campsite insurance does not insure caravans or other accommodation units on the site. These should not be treated as public buildings covered by the campsite policy.
What is static caravan insurance?
Static caravan insurance by Ripe is intended to help financially protect an individual static caravan used as a holiday home. It can cover the caravan, its contents and certain associated features against insured risks. by Ripe is intended to financially protect an individual static caravan used as a holiday home. It can cover the caravan, its contents and certain associated features against insured risks. by Ripe is intended to financially protect an individual static caravan used as a holiday home. It can cover the caravan, its contents and certain associated features against insured risks.
Cover can include:
Damage to the caravan and contents up to £175k, contents up to £30k
Underground services up to £1.5k
Debris removal up to £10k
Optional Public Liability cover up to £5 million
Optional temporary accommodation
Optional rental cover and loss of rent
Optional personal possessions cover
Decking and porches can be included within the overall insured value, subject to policy terms and limits. The product is designed for eligible UK holiday homes rather than a caravan used as a permanent main residence.
Ripe’s static caravan policy is available to individuals and cannot be taken out in a business name.
What is the main difference?
The key distinction is what is being insured and who is responsible for it.
Campsite insurance focuses on the wider site operation, including communal buildings, facilities, employees, visitors, business contents and interruption to the business.
Static caravan insurance focuses on a particular holiday caravan, including its structure, contents, decking, underground services and selected risks.
If a storm damaged a campsite’s shower block, the operator would normally look to the campsite policy. If the same storm damaged a privately owned static caravan on that site, the owner would normally look to their own static caravan policy. In both cases, cover would depend on the cause of the damage and the applicable policy terms.
Does campsite insurance cover every static caravan on the site?
You should not assume that it does. A campsite policy by Ripe can cover buildings, fixtures, equipment and other property owned or operated by the business. A privately owned static caravan is a separate asset and may need its own policy.
Does a private static caravan owner need campsite insurance?
Owning a static caravan on a campsite does not, by itself, make someone responsible for operating the campsite or maintaining its public buildings and walkways.
An individual’s caravan cover and the operator’s campsite cover address different responsibilities. The campsite’s insurance should not be assumed to cover a privately owned caravan.
What should you check before arranging cover?
Campsite operators should check which public buildings and walkways they are responsible for and how these are addressed under the policy. They should also provide accurate details about employees and any other relevant business activities or selected cover.
Individual static caravan owners should check the caravan’s value, contents, location, security arrangements and any decking or veranda. How the caravan is used also matters, including any use by paying guests.
Review the policy documents carefully to understand eligibility, insured risks, limits, excesses and exclusions. An item’s location on a campsite does not establish that it is insured.
Find both campsite and static caravan insurance by Ripe
Ripe offers specialist campsite insurance for eligible campsite businesses and static caravan insurance for eligible UK holiday home owners.
Checking who owns and operates each part of the site is the first step towards identifying which type of cover may be relevant.
Please note the information provided on this page should not be taken as advice and has been written as a matter of opinion. For more on insurance cover and policy wording, see our homepage.